Buying a Condo vs. Single-Family Home: How to Choose
Discover the Key Differences Between a Condo vs. Single-Family Home
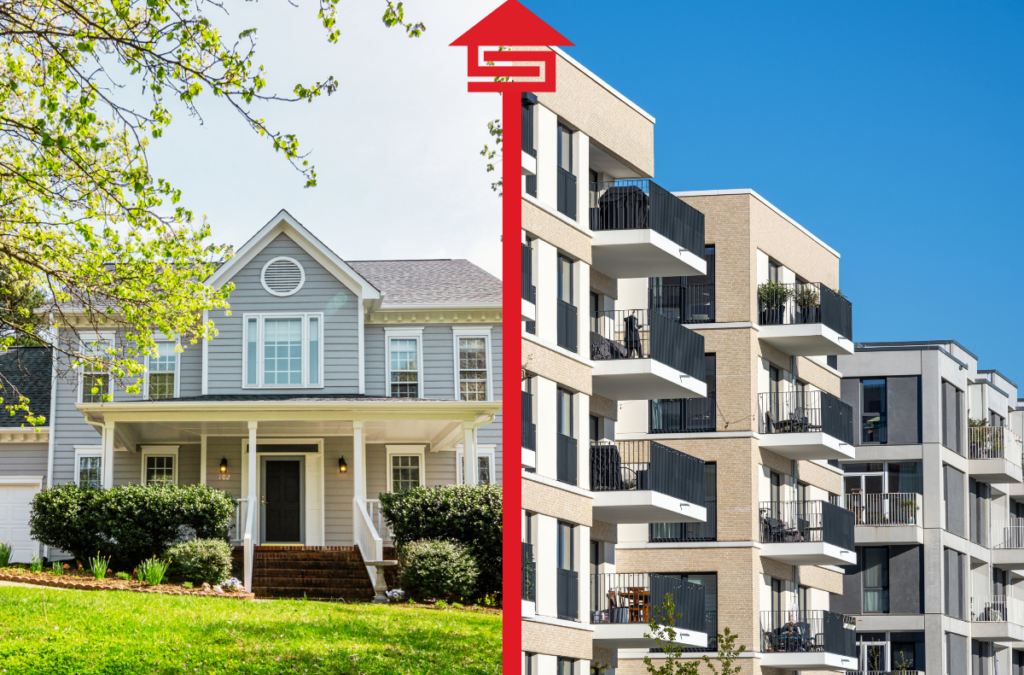
So you’ve finally decided to end the debate of renting vs. owning a home and pull the trigger on your homebuying journey. Congratulations! The next big question is deciding what kind of property you want to purchase—a condo vs. single-family home. Both options offer the potential to build equity, but the right choice comes down to your lifestyle, budget, and long-term goals.
To help you decide, here’s an overview the pros and cons of each option and how Supreme Lending may help you finance your dream home, whether it’s a condo or a single-family house.
Pros & Cons of Buying a Condo
Pros
- Lower Maintenance. One of the biggest benefits of condo living is that most exterior maintenance and landscaping are handled for you by the Homeowners Association (HOA). If you’re looking for a lower-maintenance lifestyle where you can focus on enjoying your space without the hassle of yard work or home repairs, you may want to consider a condo.
- Amenities. Many condo communities offer shared amenities such as pools, gyms, and clubhouses. This can provide luxurious perks without the extra cost of maintaining the amenities yourself.
- Affordability. In general, condos may be more affordable than single-family homes. For this reason, they are a great option for first-time homebuyers or those looking to downsize. If you’re trying to buy in a competitive housing market, a condo may offer a more budget-friendly option to open the door to homeownership.
- Location. Condos are often located in urban areas or desirable neighborhoods with easy access to dining, shopping, and public transportation. If you enjoy the vibrancy and convenience of city living, a condo can put you right in the action.
Cons
- HOA Fees. While HOAs manage the maintenance of shared spaces and amenities, that comes with a monthly cost. These fees can add up, and it’s important to factor them into your budget when considering the overall homebuying costs.
- Limited Privacy. Since condos are often in multi-unit buildings, you’ll likely be sharing a wall with neighbors. If privacy and quiet are important to you, this is something to consider.
- HOA Restrictions. HOAs typically have rules regarding what you can and cannot do with your unit, from the color of your front door to controlling whether you can rent it out. While these rules are put in place to help maintain the property’s value, they may also limit your freedom.
Pros & Cons of Buying a Single-Family Home
Pros
- More Space. Single-family homes typically offer more living space, both indoors and out. If you need room for a growing family, pets, or hobbies, or simply enjoy having a larger yard, a house may give you the space and flexibility you need.
- Privacy. Unlike condos, single-family homes can provide more privacy since you wouldn’t be sharing a wall with your neighbors. If peace and quiet are priorities, a standalone house may be your answer.
- Freedom to Personalize. As a single-family homeowner without an HOA, you have the freedom to make changes and renovations to your home. Want to build a deck, repaint your exterior, or add on more square footage? You would have the flexibility to do so.
- Suburban and Rural Living. Many single-family homes are located in suburban or rural areas. This may offer a quieter, more relaxed lifestyle away from the hustle and bustle of city life.
Cons
- Maintenance Responsibilities. With the freedom of owning a standalone property comes the responsibility for home maintenance, repairs, and upkeep. From mowing the lawn to fixing a leaky roof, you’ll be responsible for keeping everything in good condition.
- Higher Cost. Oftentimes, single-family homes may be more expensive than condos, both in terms of purchase price and ongoing costs such as property taxes, insurance, and utilities. Be sure to keep those additional costs in mind when deciding to buy a condo vs. a single-family home.
- Location. While one of the perks of single-family living is being in a more suburban or rural area, that also means you may be father away from city centers. This could result in a longer commute or less access to urban amenities.
How Do You Decide?
When choosing between a condo vs. a house, here are four helpful considerations:
- Lifestyle. Do you prefer a low-maintenance, lock-and-leave lifestyle with shared amenities? Or do you value privacy and space to personalize your property? You daily routine and personal preferences should guide your decision.
- Budget. While condos may have lower upfront costs, you’ll need to factor in HOA fees. On the other hand, single-family homes may require more financial investment in terms of ongoing maintenance.
- Location, Location, Location. Think about where you want to live. Do you prefer the convenience of urban life? Or do you dream of a suburban or rural retreat? The location has a direct impact on your lifestyle and commuting needs.
- Long-Term Goals. If you’re planning to grow your family, need extra space for hobbies, or want the freedom to make home improvements, a single-family property may make more sense. But if convenience and lower maintenance are calling your name, a condo may be the right fit.
The Benefits of Homeownership – No Matter What You Choose
Whether you opt for a condo or a standalone home, you’ll still enjoy all that homeownership has to offer. Owning your own place may give you the potential to build equity and financial stability. You’ll also have the flexibility to create a space that truly reflects your personality and lifestyle. Plus, homeownership has the potential to provide long-term rewards, as your property may appreciate in value over time.
Supreme Lending Has You Covered
Ranked as a 2024 top 15 retail lender in the country by Scotsman Guide, Supreme Lending has a wide range of mortgage options to help put people into homes—whether it’s a condo or single-family. Whatever your dream of homeownership may look like, we’re here to help with your home financing needs.
Ready to get started? Reach out to our team today!