by First Integrity Team Supreme Lending | May 10, 2025
Don’t let these condo loan myths get in your way of homeownership!
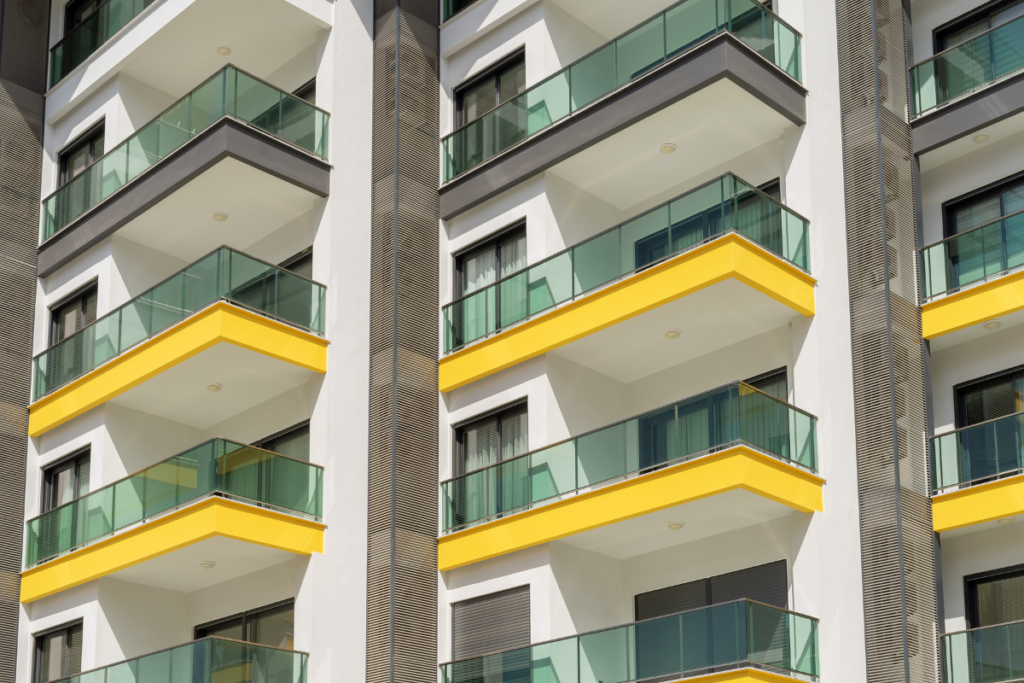
Condominiums can be an appealing alternative to traditional homes, offering perks like lower maintenance, community features, and prime locations. However, some potential homebuyers may hesitate to pursue applying for a condo loan, often due to misconceptions that it’s more challenging to secure a mortgage than a single-family home.
While getting a condo loan involves a few additional considerations, it isn’t as daunting as it may seem. With the right lender on your side, you can move through the process smoothly and confidently. At Supreme Lending, our dedicated condo team specializes in handling all the details. This will ensure your loan process is seamless from start to finish.
How Condo Financing Differs
When you apply for a mortgage on a single-family home, the lender’s primary focus is on your financing qualifications and the property itself. Condo financing, on the other hand, involves an additional layer of approval—not just on the individual unit but the overall condo complex. Lenders will review factors including:
- Homeowners Association (HOA). The financial health of the condo association and the condition of the property are evaluated to ensure the community is well-managed.
- Occupancy Rates. Lenders may require a certain percentage of units to be owner-occupied to reduce potential risks associated with high rental occupancy.
- Legal Status. The lender will also ensure there are no legal issues or disputes involving the condo association that may impact the financing process.
- Insurance Coverage. There are specific insurance requirements for the building and the association, which lenders review as part of the approval process.
These steps may add some complexity but are designed to protect both the buyer and lender. Now let’s debunk these common condo loan myths.
Myth #1 – Condo Loans Are Too Complicated
Condo loans may involve a few more steps than financing a single-family home, however they’re not as complicated as you might think. When you apply, you’ll provide basic details about the condo property, including the address. Then our specialized team at Supreme Lending will take it from there to review the complex. In some cases, you may even qualify for a limited review, which requires less paperwork and verification.
Myth #2 – Condo Underwriting Takes Took Long
The underwriting for a condo loan involves reviewing the financials, insurance, and rules of the condo’s Homeowners Association (HOA) to ensure the property is solid. While it may seem like more work, Supreme Lending’s condo team is quick to keep the process moving, helping to avoid any delays and keeping things on track.
Myth #3 – Condo Financing Is Riskier for Buyers
Some homebuyers may worry that getting a condo loan is riskier than financing a traditional home because of the HOA and shared ownership. In reality, the detailed review process can give buyers peace of mind that their condo community is financially stable and well-managed, so much so that their lender approved the condo loan.
Ready to Finance Your Dream Condo?
We’re here to help! There’s a reason why Supreme Lending offers such a wide variety of loan programs, including condo financing. Don’t let these condo loan myths hold you back. Contact us to get started today.
Related Articles:
by SupremeLending | Jun 13, 2024
Condo financing is an exciting and rewarding experience, especially if you’re looking to purchase a dream home with low maintenance and community amenities. It’s important to understand how condo loans work to make an informed decision in your homebuying journey. Let Supreme Lending help guide you through the condo financing process. Explore the steps involved, go over frequently asked questions about condo loans, and discover perks of condo living.
What Is a Condo Loan?
Condo financing is similar to traditional mortgages but comes with a few unique factors. A condo loan is specifically designed for purchasing a condominium unit. Lenders handle condo loans slightly differently due to the shared ownership structure and the condo association, also known as the homeowners’ association (HOA).
When applying for a condo mortgage, lenders will not only consider your credit report and financial profile but also the condition and management of the condo complex. This includes the association’s budget, reserves, and overall governance. A condo loan covers the unit itself and may include additional fees associated such as HOA dues.
Condo Financing Process
Here’s a quick, step-by-step guide of how condo financing works.
1. Get Pre-Qualified.
As with any mortgage, typically the first step is pre-qualification or pre-approval. This helps you understand how much home you may be able to afford and shows sellers you’re a serious, capable buyer.
2. Find the Right Condo.
Once you know your budget, search for condos that fit your preferences, location, and lifestyle. Ensure the condo is on a lender-approved list or can meet lender requirements.
3. Apply for a Loan.
Submit your full mortgage application with all required documentation, such as income verification, credit history, and details about the condo.
4. HOA Condo Review.
The lender will review the condo HOA’s financial statements, bylaws, insurance policies, and reserve funds to ensure the property is a sound investment and isn’t deemed high risk.
5. Appraisal and Inspection.
An appraisal will determine the condo’s market value, and a home inspection will help identify any potential issues with the property, such as safety hazards or systems that may not be working properly.
6. Close on the Loan.
Once all criteria are met, you’ll proceed to closing where you’ll sign the necessary documents and transfer ownership of the condo. Congratulations, you’re a condo owner!
Condo Financing FAQs
How does condo financing differ from traditional mortgages?
While similar to a conventional mortgage, a condo loan requires additional review of the condo association’s finances, bylaws, and occupancy rates. This will ensure lenders that the complex is stable and well-managed, which helps mitigate lending risks.
What’s the difference between warrantable and non-warrantable condo loans?
A warrantable condo means that the complex meets the criteria set by Fannie Mae and Freddie Mac, the government-sponsored enterprises (GSEs) that purchase and guarantee mortgages from lenders. A warrantable condo typically has at least 50% of units that are owner-occupied or second homes, and the homeowners’ association management is financially secure. Non-warrantable condos do not meet these guidelines.
Can I still finance a non-warrantable condo?
Yes. Borrowers may face unique challenges when it comes to financing non-warrantable condos, condotels, and co-ops. However, Supreme Lending offers a wide range of condo loan programs, including non-warrantable condos and FHA spot approval processing.
Can I use an FHA or VA loan to buy a condo?
Yes. There are options to finance condos through FHA or VA loans. However, the condo complex must be on an approved list by the FHA or VA. If it’s not approved by the FHA, Supreme Lending may be able to provide FHA Single-Unit Approvals to help get a condo unit approved quicker.
Are interest rates higher for condo loans?
Interest rates for condo loans may be slightly higher than single-family mortgages due to the perceived higher risk. However, rates vary based on market conditions, credit score, and individual lenders, so be sure to work with an experienced, professional Loan Officer to go over your options.
Does Supreme Lending have an in-house condo loan team?
Yes! Supreme Lending has a dedicated, in-house Condo Project Review team to manage the condo financing process. This includes reviewing the complex and HOA to make sure the property’s guidelines are met.
Benefits of Condo Living
- Community Living. Condos often foster a strong sense of community, providing ample opportunities to meet neighbors and participate in social activities.
- Lower Maintenance. The Condo’s HOA typically handles exterior maintenance such as landscaping and select repairs, freeing you from traditional homeownership responsibilities.
- Condos can offer several amenities such as swimming pools, gyms, and recreational areas, allowing you to enjoy these perks without the personal investment or upkeep.
- Prime Locations. Condos are often located in desirable, urban areas, offering convenient proximity to work, entertainment, and dining options.
Condo financing can unlock the door to a vibrant and accessible lifestyle. By understanding the ins and outs of the condo loan process, you can be equipped with knowledge and power to make informed decisions. At Supreme Lending, we’re here to help guide you through every step of condo financing.
by SupremeLending | Feb 21, 2024
Condominiums—commonly known as condos—are a great option for homebuyers looking for less maintenance, urban settings, lock-and-leave lifestyle, and community amenities. But the differences between financing condos and single-family homes may bring more complexity to the condo loan process.
Condos are privately-owned units within a building where residents have ownership of their interior space and share ownership of common areas and exterior space (i.e., pool, roof, landscaping). Condo buildings are typically managed by a homeowner’s association (HOA). Upkeep of the common areas can be funded through monthly HOA fees, which are in addition to a resident’s mortgage payment.
The condo loan process typically considers several more factors than the process for a single-family home. Down payment minimums and interest rates may be higher for condo loans too. When financing a condo, lenders will not only look at the buyer’s financial history but may also evaluate the condo community’s condition and finances.
Several types of loans have requirements that condo associations must meet for a lender to be able to provide financing, which identify the condo as “warrantable.” If a condo property doesn’t follow specified guidelines, lenders, including Supreme Lending, can offer condo loan options for non-warrantable properties if eligible. Condo loan options include Conventional, FHA, VA, and new construction.
While the condo loan process may be more complex, Supreme Lending has an experienced in-house Project Review Office team dedicated to helping speed up the process by gathering and processing required documents for condo loans for a smooth homebuying experience.
Are you looking to finance a condo now or in the future? Contact your local Supreme Lending branch to get started.